ECB Raises Interest Rates to 2.5% for Second Time This Year as Middle East War Fuels Inflation
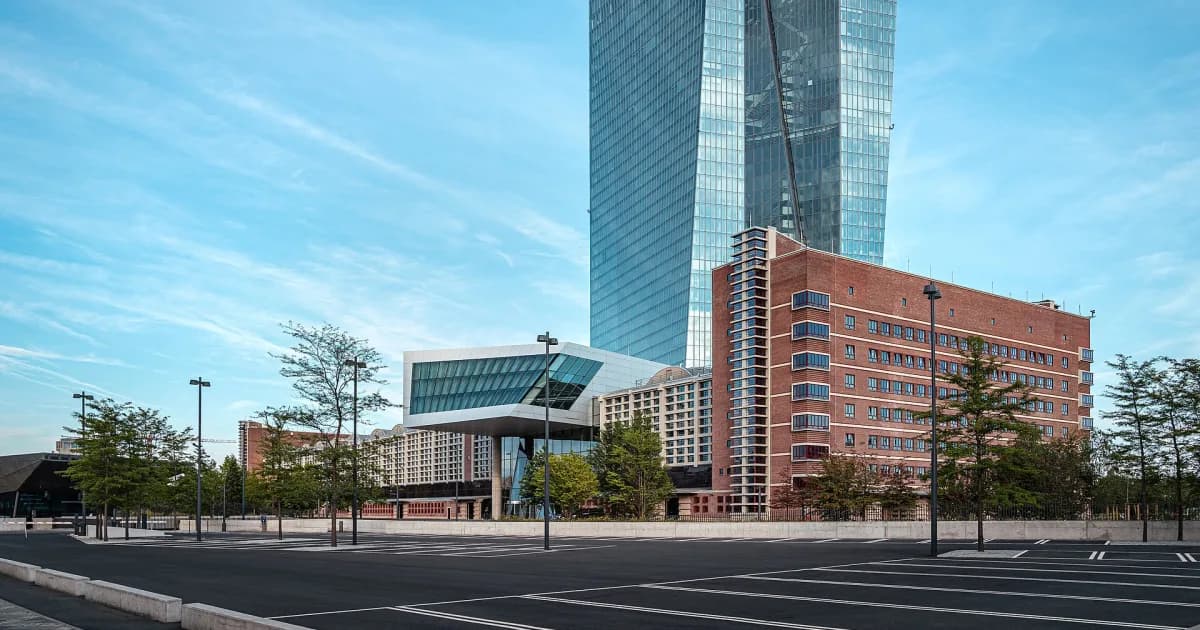
The European Central Bank raised interest rates by 25 basis points on Thursday, lifting its deposit facility rate to 2.5% and signalling that inflation will remain well above its 2% target for an extended period.
The move, which takes effect from September 16, is the second rate hike this year and comes as the bank contends with rising prices, the consequences of the US-Iran war and surging government borrowing costs across the West.
"The conflict in the Middle East continues to generate inflation pressures, and inflation is set to remain well above target for an extended period," the ECB said in its statement, adding that the decision underscores its commitment to ensuring inflation stabilises at 2% in the medium term.
The bank explained that tension in the region increases uncertainty, warning of upside risks to inflation and downside risks to economic growth.
## Inflation Forecasts Pushed Higher
The ECB now expects headline inflation of 3.0% this year, 2.5% in 2027 and 2.1% in 2028, with the Middle East conflict keeping pressure on energy prices. When the war began in late February, eurozone inflation stood at 1.9%, but it has remained above the bank's 2% target ever since, while core inflation, which strips out volatile food and energy prices, has remained broadly stable.
President Christine Lagarde said the outlook remains uncertain, and the bank stressed that it is "not pre-committing to a particular rate path."
The war's energy shock has already forced other major central banks into action. The surge in energy prices has sharpened the focus on the ECB's own tightening path, and financial markets expect the US Federal Reserve to raise borrowing costs for the first time since 2023, with America's 10-year Treasury yield breaching 5% and long-term UK government borrowing costs at their highest levels in decades.
## Policymakers Signal More Could Follow
Governors were quick to frame the door as open for further tightening. Bank of Latvia Governor Martins Kazaks, a Governing Council member, said the case for further rate hikes is "growing," signalling a move into restrictive territory.
Markets have taken the hint: Barclays predicts the ECB will raise rates by another 25 basis points in December, citing persistent inflation and rising energy prices driven by Middle East tensions.
Analysts at ING noted that at 2.5%, the main policy rate now sits at the upper bound of the range the central bank itself considers neutral, meaning every further move would push borrowing costs into restrictive ground that actively slows the economy.
For households across the euro area, another rate hike means more expensive mortgages, consumer credit and other loans, and the bank has faced criticism in some quarters for trying to tackle an energy-driven price shock with an interest rate tool that does nothing to increase the supply of oil and gas.
## The Rate Hike That Pays Nothing: Europe's Stablecoins
Thursday's decision also spotlighted a quirk of Europe's regulated crypto market. Under the EU's MiCA framework, euro stablecoins such as Circle's EURC are classed as e-money tokens, and Article 50 bars issuers and crypto platforms from paying holders interest. The rule even covers benefits or discounts tied to how long a token is held: "any remuneration or any other benefit related to the length of time" a token is held can count as interest.
Issuers must instead safeguard the money backing those tokens, with at least 30% required to remain in bank deposits and the rest in secure, highly liquid, low-risk assets whose returns flow to the issuer, not the holder. Circle has operated EURC under a French e-money licence since July 2024, and its market value now stands at roughly $466 million.
When MiCA's stablecoin rules took effect in June 2024, the ECB deposit rate stood at 3.75%. Thursday's move takes the gap between the ECB deposit rate and the permitted holder yield back to 250 basis points, a split that leaves euro stablecoin holders earning exactly zero however far the bank pushes rates.
## A Delicate Balance Between Prices and Growth
The decision highlights the narrow path facing the Governing Council. Inflation is being driven from outside the currency bloc by war-disrupted energy markets, yet the bank's mandate ties it to the 2% target regardless of the source. At the same time, the warning of downside risks to growth acknowledges that higher rates and costlier energy are weighing on an economy that has yet to absorb the full impact of the conflict.
The bank's updated projections embody that tension: inflation is not expected to return to target until around 2028, while the rate path required to get there risks compounding the growth weakness the ECB itself flags. With Kazaks and market economists alike pointing toward further increases, the question for the December meeting is less whether the hiking cycle continues than how far into restrictive territory the Governing Council is prepared to go while the war keeps energy prices elevated.
Discussion
Recommended for you
More business
Finance
US Tech Giants Turn to Euro Bond Market as AI Debt Wave Reshapes Credit
9/16/2026
Finance
Rising Bond Yields and Geopolitical Tensions Weigh on Global Market Sentiment
9/2/2026
Finance
US Consumer Confidence Falls to 94.2 as Inflation and Hiring Worries Grip Households
9/2/2026
Finance